Overview
The Portfolio Investment Entity (PIE) income workpaper is used to record PIE income for IR4 and IR6 tax return types.
For entities filing IR4 and IR6 returns, the workpaper is used to record PIE income or loss and PIE tax deducted. The PIE income can be marked as Taxable or Excluded, and it flows through to the tax return and tax calculation automatically.
You need to determine what the correct PIE tax treatment is. For guidance on the tax treatment of PIE income we suggest you review IR’s website.
See Add a PIE income workpaper to an individual for information on adding a PIE income workpaper to an IR3.
Add a PIE income workpaper
A PIE income workpaper can be added directly to a trial balance account or as a standalone workpaper.
Once the workpaper has been added:
- In the PIE income workpaper, select whether the PIE income is Taxable or Excluded.
- Enter the Portfolio Investment Entity income or (loss).
- Enter the PIE tax (deducted) or credited.
- Optional: add a query, note or file and sign off the workpaper.
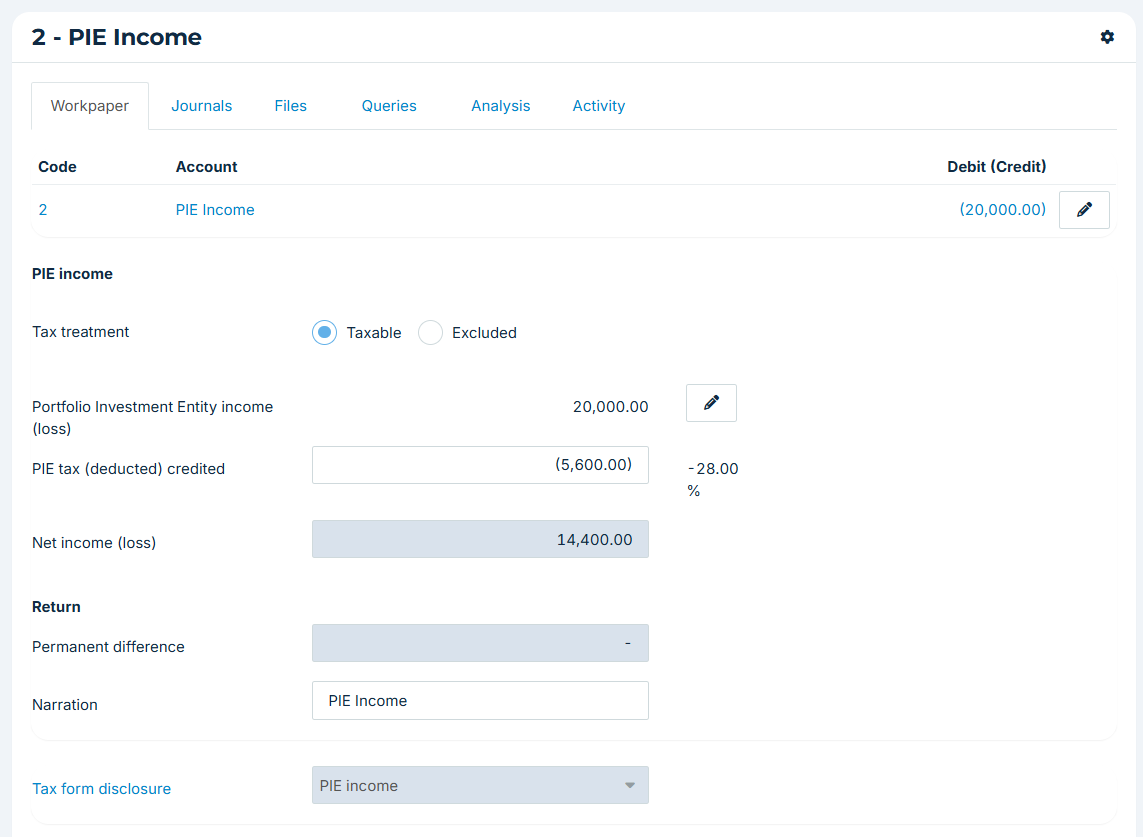
The software automatically populates the tax return and tax calculation with the entered PIE income and PIE tax withheld.
In a trust, PIE income and credits will be aggregated into Other income and Other credits for the purposes of distributing to beneficiaries.
Other credits
Any FTCs, RWT or ICs withheld on PIE income will need to be declared through the appropriate workpapers.
Troubleshooting
Issue: I need to add PIE income into other returns.
PIE income is not currently supported in the below returns, but can be filed using other workpaper types:
- Non-resident individual (IR3NR): this is not currently supported because of the variable limit on the allowable tax credits. Use an Other income workpaper if PIE income and credits need to be included in the return.
- Partnership or Look-through company (IR7): this is not currently supported because partnerships and LTC PIE interests are held by the partners/shareholders and should be declared directly in their respective returns.
- Maori Authority (IR8) or Club and society (IR9): Use an Other income workpaper if PIE income and credits need to be included in the return.
See Add a PIE income workpaper to an individual for information on adding a PIE income workpaper to an IR3.
For more information, refer to the PIE guidance on the Inland Revenue (IR) website.
Was this article helpful?
That’s Great!
Thank you for your feedback
Sorry! We couldn't be helpful
Thank you for your feedback
Feedback sent
We appreciate your effort and will try to fix the article